Mounted Bearing Market Size & Share Growth Forecast Report (2026-2035)
Industry Insight by Product Type (Ball Bearings, Roller Bearings, Plain Bearings, Others), by Housing Material (Cast Iron, Stainless Steel, Thermoplastic or Polymer, Pressed Steel), by Distribution Channel (OEM, Aftermarket), by End User (Industrial Machinery, Agriculture, Food and Beverage, Mining and Construction, Automotive, Others)
| Status : Published | Published On : Oct, 2026 | Report Code : VRICT5248 | Industry : ICT & Media | Available Format :

|
Page : 154 |
Mounted Bearing Market Overview
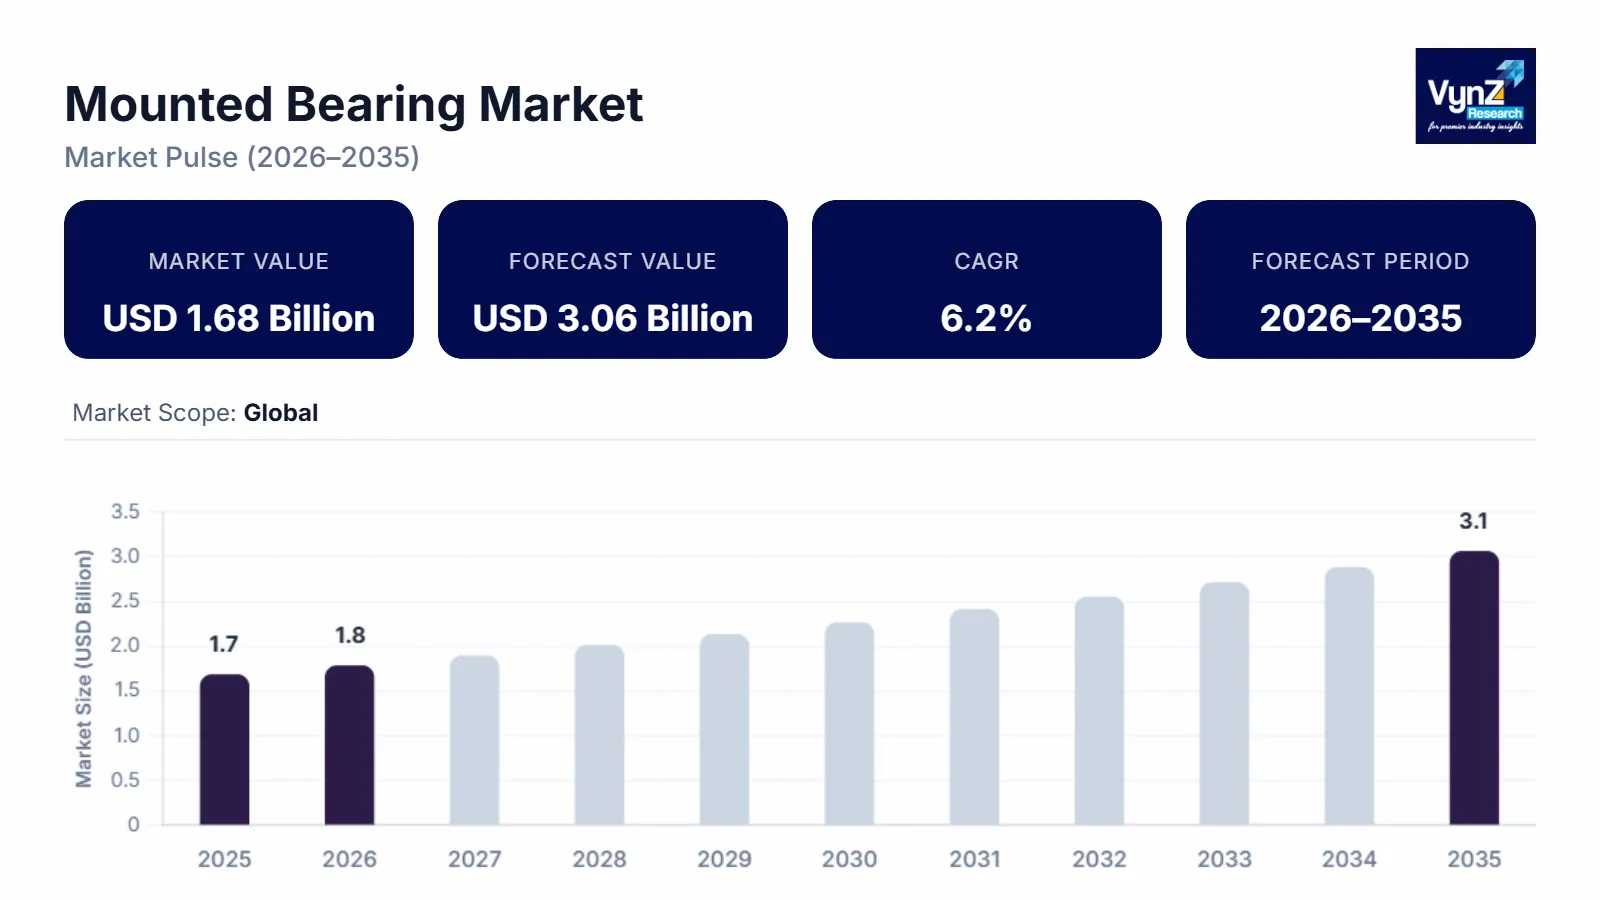
The mounted bearing market size was estimated at about USD 1.68 billion in 2025 and is expected to reach around USD 1.78 billion in 2026, rising up to roughly USD 3.06 billion in 2035, growing at approximately 6.2% CAGR from 2026 to 2035, with 2025 as the base year and 2035 as the forecast year.
The industry is being driven by growing machinery production, conveyor-based material handling, agricultural mechanization, food processing, and the need for simplified bearing installation. The demand is also being driven by the need for sealed, corrosion-resistant, and low-maintenance bearing units that contribute to high equipment availability and reduced service intervals.
The industry expansion is primarily fueled by industrial machinery growth, automation, agricultural mechanization, and the rising need for conveyor-based material handling, as well as the growing need for sealed and maintenance-friendly bearing assemblies. Surges in manufacturing activity in China are also projected to propel the bearing market expansion. According to the National Bureau of Statistics of China, general-purpose machinery manufacturing grew by 8% year-over-year in 2025, while special-purpose machinery manufacturing grew by 4.3%. Additionally, India’s expansion in manufacturing activity is also expected to benefit the market as the nation’s Index of Industrial Production, as tracked by the Ministry of Statistics and Program Implementation, also reflects a rise in manufacturing activity. These trends are also linked to the need for machinery that utilizes bearings.
Research Methodology
VynZ Research uses secondary research, industry analysis, company repositories, government publications, and comparable studies examining bearing demand in different machinery-intensive end-markets to inform its understanding of the market. To arrive at its estimates, the VynZ Research team then takes into account the bearing’s configuration, housing material, sales channel, application, industrial production rates, and replacement demand. The market size projections for 2020-2024 were determined using the 2025 year, whereas the forecast for 2026-2035 was conducted using industrialization, automation, agricultural machinery, food processing, mining, and technological advances that are likely to influence the need for bearings and their efficacy.
Research Highlights
- Ball bearings accounted for an estimated 64.2% of product type revenue in 2025, supported by broad use across conveyors, agricultural equipment and general industrial machinery.
- Cast iron housings represented an estimated 69.2% of housing material demand in 2025, reflecting their load carrying capability and established use in industrial equipment.
- OEM distribution accounted for an estimated 67.4% of sales in 2025, due to direct specification of mounted units during machinery manufacturing and equipment integration.
- Roller bearing mounted units are projected to register approximately 6.7% CAGR from 2026 to 2035, for higher load requirements in mining, construction and heavy machinery.
- Asia Pacific accounted for an estimated 43.0% of global revenue in 2025, driven by manufacturing expansion, machinery production and industrial automation across China, India, Japan and other major markets.
Mounted Bearing Market Dynamics
Market Trends
The industry is witnessing a gradual shift toward bearing assemblies that combine simplified installation with longer operating life, contamination resistance and lower maintenance requirements. Preassembled mounted units reduce the need for separately machined housings and can shorten equipment servicing procedures, making them suitable for conveyors, agricultural machinery, processing equipment and general industrial applications. Another notable trend is the integration of condition monitoring into bearing maintenance programs, particularly where unexpected equipment stoppages can create substantial production losses. NTN has expanded its portable vibration monitoring offering for industrial equipment, while manufacturers are increasingly connecting bearing condition assessment with predictive maintenance practices.
Growth Drivers
The growth of the market is largely supported by industrial machinery production, which continues to generate demand for bearing units across manufacturing plants, material handling systems, agricultural equipment and processing lines. China recorded 9.2% growth in equipment manufacturing value added during 2025, according to the National Bureau of Statistics, while general-purpose machinery manufacturing increased 8%. Such expansion increases the installed base of rotating machinery and creates both original equipment and replacement demand. The European Union also recorded a 3.3% increase in machinery and equipment production value in 2025, according to Eurostat, reinforcing the importance of machinery investment across established industrial markets. Additionally, the expansion of food processing, agriculture, mining and construction equipment is supporting demand for housed bearing assemblies capable of operating under dust, moisture, vibration and heavy load conditions.
Market Restraints / Challenges
Despite favorable growth prospects, the market faces challenges from raw material costs, manufacturing expenses and fluctuations in industrial capital expenditure. Bearing assemblies depend heavily on steel, cast iron, seals, lubrication materials and precision manufacturing processes, making producers sensitive to changes in material and energy costs. The National Bureau of Statistics of China reported that industrial enterprise profits remained under pressure in several manufacturing categories during 2025, even as general purpose machinery and special purpose machinery activity expanded. Cost pressure can encourage buyers to extend replacement intervals, select lower-cost products or defer nonessential equipment upgrades, particularly among smaller industrial operators. Furthermore, supply chain dependence and technical requirements create operational challenges for manufacturers and distributors.
Market Opportunities
The market presents significant opportunities in predictive maintenance, corrosion-resistant housings, food-grade applications and high-load-bearing assemblies, particularly as industrial operators seek to reduce unplanned downtime. Opportunities exist in food and beverage processing, where hygienic designs and improved sealing can address demanding operating conditions. Companies that combine standard mounted units with application engineering and maintenance services can capture additional demand from customers seeking simplified procurement and equipment reliability. Another key opportunity lies in industrial automation, energy-efficient machinery and equipment modernization, where compact and lower-friction bearing solutions can improve operating performance.
Global Mounted Bearing Market Report Coverage
|
Report Metric |
Details |
|
Historical Period |
2020 - 2024 |
|
Base Year Considered |
2025 |
|
Forecast Period |
2026 - 2035 |
|
Market Size in 2025 |
USD 1.68 Billion |
|
Revenue Forecast in 2035 |
USD 3.06 Billion |
|
Growth Rate |
6.2% |
|
Segments Covered in the Report |
Product Type, Housing Material, Distribution Channel, End User |
|
Report Scope |
Market Trends, Drivers, and Restraints; Revenue Estimation and Forecast; Segmentation Analysis; Companies’ Strategic Developments; Market Share Analysis of Key Players; Company Profiling |
|
Regions Covered in the Report |
North America, Europe, Asia Pacific, Rest of the World |
|
Key Companies |
Altra Industrial Motion Corp, Baldor Electric Company, Climax Metal Products Company, Dodge Industrial Inc, FYH Inc, JTEKT Corporation, NSK Ltd, NTN Corporation, Schaeffler AG, The Timken Company |
|
Customization |
Available upon request |
Mounted Bearing Market Segmentation
By Product Type
Ball bearings accounted for an estimated 64.2% share in 2025, supported by broad application across conveyors, agricultural equipment, general machinery and material handling systems. Their relatively simple construction, wide availability and suitability for moderate load and speed requirements support continued demand.
Roller bearing mounted units are projected to record approximately 6.7% CAGR from 2026 to 2035, making them the fastest-growing product category as heavy-duty machinery becomes more prevalent.
By Housing Material
Cast iron held an estimated 69.2% share in 2025 because of its established use in industrial machinery, conveyor systems and agricultural equipment where strength, rigidity and cost considerations remain important.
Stainless steel housing demand is expected to expand at approximately 6.8% CAGR from 2026 to 2035, supported by increased requirements for corrosion resistance and hygienic equipment design.
By Distribution Channel
OEM sales accounted for an estimated 67.4% share in 2025, reflecting the importance of mounted bearing specification during the design and manufacture of conveyors, agricultural machinery, industrial equipment and processing systems.
The aftermarket channel is projected to register approximately 7% CAGR from 2026 to 2035, supported by the expanding installed base of industrial machinery and greater emphasis on predictive maintenance.
By End User
Food and beverage represented an estimated 24.3% share in 2025, while industrial machinery and agriculture remained major demand contributors because of extensive use of conveyors, pumps, processing equipment and rotating machinery.
Mining and construction are projected to record approximately 6.6% CAGR from 2026 to 2035, supported by equipment modernization and the increasing use of heavy-duty machinery. Demand for stronger bearing assemblies is reinforced by applications such as crushers, conveyors and material handling equipment.
Regional Insights
North America
North America accounted for an estimated 26% of the market in 2025, supported by a large installed base of industrial machinery, agricultural equipment, conveyors, mining systems and replacement applications. The United States remains an important demand center because of its mature manufacturing and industrial maintenance ecosystem. The U.S. Bureau of Economic Analysis reported that manufacturing recorded the largest increase in the foreign direct investment position in the United States by industry during 2025, while manufacturing also represented 52.5% of new investment expenditures. These investment patterns support equipment modernization and recurring demand for bearing components.
Europe
Europe represented an estimated 19% share of global revenue in 2025, supported by established machinery manufacturing, food processing, automotive production and industrial maintenance activities. Eurostat reported that the value of EU sold industrial production increased 2.9% in constant prices during 2025, while machinery and equipment recorded a 3.3% increase. These trends indicate improving industrial activity across an important installed market for bearing assemblies. Germany, Italy and other manufacturing economies continue to support demand for engineered components used in machine tools, conveyors, production systems and specialized equipment.
Asia Pacific
Asia Pacific accounted for an estimated 43% share in 2025 and is projected to remain the fastest-growing regional market, supported by manufacturing expansion, industrial automation and machinery production. China recorded 5.9% growth in industrial value added during 2025, with equipment manufacturing increasing 9.2%, while industrial robot output increased 28.0%. India also continues to strengthen its manufacturing base, with the Ministry of Statistics and Program Implementation maintaining industrial production measurement across manufacturing, mining and electricity. These developments support demand for mounted bearings across factory automation, material handling, agricultural equipment and general industrial machinery.
Rest of the World
The Rest of the World accounted for the remaining estimated 12% of global revenue in 2025, covering Latin America, the Middle East and Africa. Demand is supported by agriculture, mining, food processing, construction, energy infrastructure and material handling activities, although market development varies considerably between individual economies. Equipment replacement requirements and investment in industrial facilities provide recurring opportunities for mounted bearing suppliers, particularly where machinery operates under dust, moisture, heavy loads or difficult maintenance conditions.
Competitive Landscape / Company Insights
The market is moderately to highly competitive, with global bearing manufacturers and specialized regional suppliers competing through product breadth, application engineering, distribution coverage and aftermarket support. Companies are investing in lower friction designs, improved sealing, corrosion resistance, condition monitoring and higher load capacity to address changing industrial requirements. Timken has expanded mounted bearing solutions for agriculture, food and beverage, conveyors and heavy industry, while Schaeffler, NSK, NTN and JTEKT continue developing application-specific bearing technologies. Competition is increasingly influenced by lifecycle performance, technical support and availability in addition to product pricing.
Mini Profiles
Altra Industrial Motion Corp provides power transmission and motion control solutions, including bearing related products, serving industrial customers through a broad application portfolio and established distribution capabilities.
Baldor Electric Company supplies mounted bearing and related mechanical power transmission products, with its offering positioned across industrial machinery, conveying and motor driven equipment applications.
Climax Metal Products Company develops bearing accessories and mechanical components for industrial applications, supporting customers requiring standardized and application specific shaft support solutions.
Dodge Industrial Inc specializes in mounted bearings and mechanical power transmission products, serving conveyors, material handling, agriculture, food processing and other industrial applications.
FYH Inc focuses on mounted bearing units and related products, with a broad range of housed bearing solutions designed for machinery, agricultural equipment and material handling applications.
Key Players
- Altra Industrial Motion Corp
- Baldor Electric Company
- Climax Metal Products Company
- Dodge Industrial Inc
- FYH Inc
- JTEKT Corporation
- NSK Ltd
- NTN Corporation
- Schaeffler AG
- The Timken Company
Recent Developments
JTEKT Corporation continues to advance compact and low-friction bearing technologies for changing mobility and industrial requirements. Its 2025 engineering work includes compact bearing development and technologies designed to improve efficiency, reliability and resistance to electrically induced damage.
NSK Ltd developed a compact, lightweight deep groove ball bearing for electric vehicle drive units, targeting lower friction, reduced size and weight, and higher speed operation. The company also introduced reconditioning-focused bearing technology for demanding mining equipment, supporting longer product life and reduced maintenance requirements.
NTN Corporation started mass production of a low-dust-generation bearing for servo motors used in industrial robots, machine tools and semiconductor manufacturing equipment. The company also expanded condition monitoring capabilities through its portable vibration monitoring system for detecting bearing abnormalities and supporting predictive maintenance.
Schaeffler AG expanded its bearing portfolio for machine tools and automation, including new precision angular contact ball bearings and ceramic rolling element solutions. The company has also expanded localized industrial bearing production in India, including large-size spherical roller bearings, housings and accessories for heavy-duty sectors.
The Timken Company expanded its mounted bearing portfolio across corrosion-resistant, hygienic, agricultural, conveyor and heavy-duty applications. The company is also investigating new coatings and polymer materials aimed at easier installation, removal and improved performance in demanding food and industrial applications.
Global Mounted Bearing Market Coverage
Product Type Insight and Forecast 2026 - 2035
- Ball Bearings
- Roller Bearings
- Plain Bearings
- Others
Housing Material Insight and Forecast 2026 - 2035
- Cast Iron
- Stainless Steel
- Thermoplastic or Polymer
- Pressed Steel
Distribution Channel Insight and Forecast 2026 - 2035
- OEM
- Aftermarket
End User Insight and Forecast 2026 - 2035
- Industrial Machinery
- Agriculture
- Food and Beverage
- Mining and Construction
- Automotive
- Others
Global Mounted Bearing Market by Region
- North America
- By Product Type
- By Housing Material
- By Distribution Channel
- By End User
- By Country - U.S., Canada, Mexico
- Europe
- By Product Type
- By Housing Material
- By Distribution Channel
- By End User
- By Country - Germany, U.K., France, Italy, Spain, Russia, Rest of Europe
- Asia-Pacific (APAC)
- By Product Type
- By Housing Material
- By Distribution Channel
- By End User
- By Country - China, Japan, India, South Korea, Vietnam, Thailand, Malaysia, Rest of Asia-Pacific
- Rest of the World (RoW)
- By Product Type
- By Housing Material
- By Distribution Channel
- By End User
- By Country - Brazil, Saudi Arabia, South Africa, U.A.E., Other Countries
Table of Contents for Mounted Bearing Market Report
1. Research Overview
1.1. The Report Offers
1.2. Market Coverage
1.2.1. By
Product Type
1.2.2. By
Housing Material
1.2.3. By
Distribution Channel
1.2.4. By
End User
1.3. Research Phases
1.4. Limitations
1.5. Market Methodology
1.5.1. Data Sources
1.5.1.1.
Primary Research
1.5.1.2.
Secondary Research
1.5.2. Methodology
1.5.2.1.
Data Exploration
1.5.2.2.
Forecast Parameters
1.5.2.3.
Data Validation
1.5.2.4.
Assumptions
1.5.3. Study Period & Data Reporting Unit
2. Executive Summary
3. Industry Overview
3.1. Industry Dynamics
3.1.1. Market Growth Drivers
3.1.2. Market Restraints
3.1.3. Key Market Trends
3.1.4. Major Opportunities
3.2. Industry Ecosystem
3.2.1. Porter’s Five Forces Analysis
3.2.2. Recent Development Analysis
3.2.3. Value Chain Analysis
3.3. Competitive Insight
3.3.1. Competitive Position of Industry
Players
3.3.2. Market Attractive Analysis
3.3.3. Market Share Analysis
4. Global Market Estimate and Forecast
4.1. Global Market Overview
4.2. Global Market Estimate and Forecast to 2035
5. Market Segmentation Estimate and Forecast
5.1. By Product Type
5.1.1. Ball Bearings
5.1.1.1. Market Definition
5.1.1.2. Market Estimation and Forecast to 2035
5.1.2. Roller Bearings
5.1.2.1. Market Definition
5.1.2.2. Market Estimation and Forecast to 2035
5.1.3. Plain Bearings
5.1.3.1. Market Definition
5.1.3.2. Market Estimation and Forecast to 2035
5.1.4. Others
5.1.4.1. Market Definition
5.1.4.2. Market Estimation and Forecast to 2035
5.2. By Housing Material
5.2.1. Cast Iron
5.2.1.1. Market Definition
5.2.1.2. Market Estimation and Forecast to 2035
5.2.2. Stainless Steel
5.2.2.1. Market Definition
5.2.2.2. Market Estimation and Forecast to 2035
5.2.3. Thermoplastic or Polymer
5.2.3.1. Market Definition
5.2.3.2. Market Estimation and Forecast to 2035
5.2.4. Pressed Steel
5.2.4.1. Market Definition
5.2.4.2. Market Estimation and Forecast to 2035
5.3. By Distribution Channel
5.3.1. OEM
5.3.1.1. Market Definition
5.3.1.2. Market Estimation and Forecast to 2035
5.3.2. Aftermarket
5.3.2.1. Market Definition
5.3.2.2. Market Estimation and Forecast to 2035
5.4. By End User
5.4.1. Industrial Machinery
5.4.1.1. Market Definition
5.4.1.2. Market Estimation and Forecast to 2035
5.4.2. Agriculture
5.4.2.1. Market Definition
5.4.2.2. Market Estimation and Forecast to 2035
5.4.3. Food and Beverage
5.4.3.1. Market Definition
5.4.3.2. Market Estimation and Forecast to 2035
5.4.4. Mining and Construction
5.4.4.1. Market Definition
5.4.4.2. Market Estimation and Forecast to 2035
5.4.5. Automotive
5.4.5.1. Market Definition
5.4.5.2. Market Estimation and Forecast to 2035
5.4.6. Others
5.4.6.1. Market Definition
5.4.6.2. Market Estimation and Forecast to 2035
6. North America Market Estimate and Forecast
6.1. By
Product Type
6.2. By
Housing Material
6.3. By
Distribution Channel
6.4. By
End User
6.4.1.
U.S. Market Estimate and Forecast
6.4.2.
Canada Market Estimate and Forecast
6.4.3.
Mexico Market Estimate and Forecast
7. Europe Market Estimate and Forecast
7.1. By
Product Type
7.2. By
Housing Material
7.3. By
Distribution Channel
7.4. By
End User
7.4.1.
Germany Market Estimate and Forecast
7.4.2.
France Market Estimate and Forecast
7.4.3.
U.K. Market Estimate and Forecast
7.4.4.
Italy Market Estimate and Forecast
7.4.5.
Spain Market Estimate and Forecast
7.4.6.
Russia Market Estimate and Forecast
7.4.7.
Rest of Europe Market Estimate and Forecast
8. Asia-Pacific (APAC) Market Estimate and Forecast
8.1. By
Product Type
8.2. By
Housing Material
8.3. By
Distribution Channel
8.4. By
End User
8.4.1.
China Market Estimate and Forecast
8.4.2.
Japan Market Estimate and Forecast
8.4.3.
India Market Estimate and Forecast
8.4.4.
South Korea Market Estimate and Forecast
8.4.5.
Rest of Asia-Pacific Market Estimate and Forecast
9. Rest of the World (RoW) Market Estimate and Forecast
9.1. By
Product Type
9.2. By
Housing Material
9.3. By
Distribution Channel
9.4. By
End User
9.4.1.
Brazil Market Estimate and Forecast
9.4.2.
Saudi Arabia Market Estimate and Forecast
9.4.3.
South Africa Market Estimate and Forecast
9.4.4.
U.A.E. Market Estimate and Forecast
9.4.5.
Other Countries Market Estimate and Forecast
10. Company Profiles
10.1.
Altra Industrial Motion Corp.
10.1.1.
Snapshot
10.1.2.
Overview
10.1.3.
Offerings
10.1.4.
Financial
Insight
10.1.5.
Recent
Developments
10.2.
Baldor Electric Company
10.2.1.
Snapshot
10.2.2.
Overview
10.2.3.
Offerings
10.2.4.
Financial
Insight
10.2.5.
Recent
Developments
10.3.
Climax Metal Products Company
10.3.1.
Snapshot
10.3.2.
Overview
10.3.3.
Offerings
10.3.4.
Financial
Insight
10.3.5.
Recent
Developments
10.4.
Dodge Industrial Inc.
10.4.1.
Snapshot
10.4.2.
Overview
10.4.3.
Offerings
10.4.4.
Financial
Insight
10.4.5.
Recent
Developments
10.5.
FYH Inc.
10.5.1.
Snapshot
10.5.2.
Overview
10.5.3.
Offerings
10.5.4.
Financial
Insight
10.5.5.
Recent
Developments
10.6.
JTEKT Corporation
10.6.1.
Snapshot
10.6.2.
Overview
10.6.3.
Offerings
10.6.4.
Financial
Insight
10.6.5.
Recent
Developments
10.7.
NSK Ltd.
10.7.1.
Snapshot
10.7.2.
Overview
10.7.3.
Offerings
10.7.4.
Financial
Insight
10.7.5.
Recent
Developments
10.8.
NTN Corporation
10.8.1.
Snapshot
10.8.2.
Overview
10.8.3.
Offerings
10.8.4.
Financial
Insight
10.8.5.
Recent
Developments
10.9.
Schaeffler AG
10.9.1.
Snapshot
10.9.2.
Overview
10.9.3.
Offerings
10.9.4.
Financial
Insight
10.9.5.
Recent
Developments
10.10.
The Timken Company
10.10.1.
Snapshot
10.10.2.
Overview
10.10.3.
Offerings
10.10.4.
Financial
Insight
10.10.5.
Recent
Developments
11. Appendix
11.1. Exchange Rates
11.2. Abbreviations
Note: Financial insight and recent developments of different companies are subject to the availability of information in the secondary domain.
Frequently Asked Questions
Purchase Options
Latest Report
Research Methodology
- Desk Research / Pilot Interviews
- Build Market Size Model
- Research and Analysis
- Final Deliverable
Connect With Our Sales Team
- Toll-Free: +1-888-253-3960
- Phone: +91 9960 288 381
- Email: enquiry@vynzresearch.com
Mounted Bearing Market